
The Navigator provides insight into stock market events with an outlook.
July 7, 2025
“Tariff Shock.” Within just a few weeks, the market experienced one of the sharpest declines and the strongest recoveries in recent history—triggered, exacerbated, and ultimately offset by the same source: Washington’s trade policy. As the first half of the year draws to a close, the U.S. dollar has posted its weakest first half since 1973, gold is racing toward record highs, and the market is proving to be more resilient than the headlines would suggest.
Market review
The first half of 2025 began with a shock that very few had anticipated on such a scale. As early as the end of January, the announcement of the Chinese AI model DeepSeek triggered one of the largest single-day losses in stock market history: Nvidia lost about 17 percent—or nearly $600 billion—in market capitalization in a single day, while the Nasdaq fell by about 3 percent. This was a first taste of just how nervous and focused the market has become in its reaction to the few major tech stocks that have driven the indices in recent years.
The real breaking point, however, came on April 2—a day the U.S. government itself referred to as “Liberation Day”: a global base tariff of 10 percent, plus country-specific “reciprocal” tariff rates ranging from 10 to 46 percent—and at times as high as 145 percent against China—caused the S&P 500 to plunge by about 10 to 12 percent within two trading days, marking the largest two-day drop in the index’s history. Approximately $6.6 trillion in market capitalization vanished into thin air. China responded immediately with its own 34 percent tariffs. The market reaction was so severe that the government announced a 90-day pause on the reciprocal tariffs just a few days later—and the market responded with one of the strongest single-day rallies in decades (+9.5 percent). By the end of April, the S&P 500 was down only 0.76 percent—as if nothing had happened.
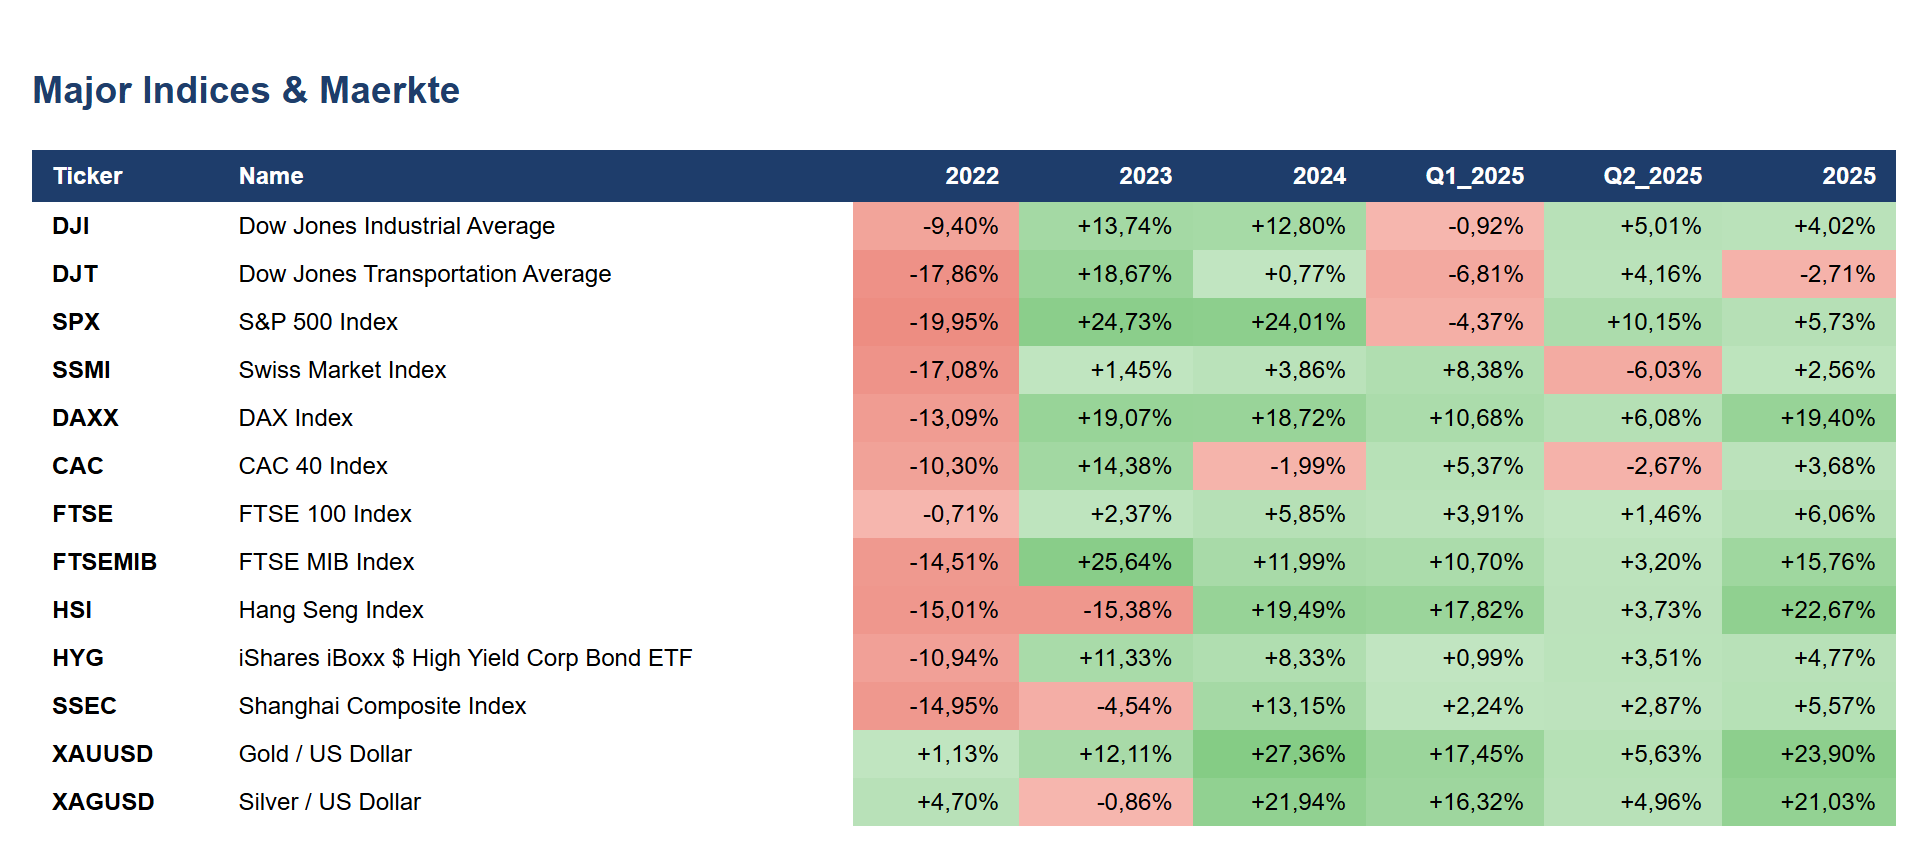
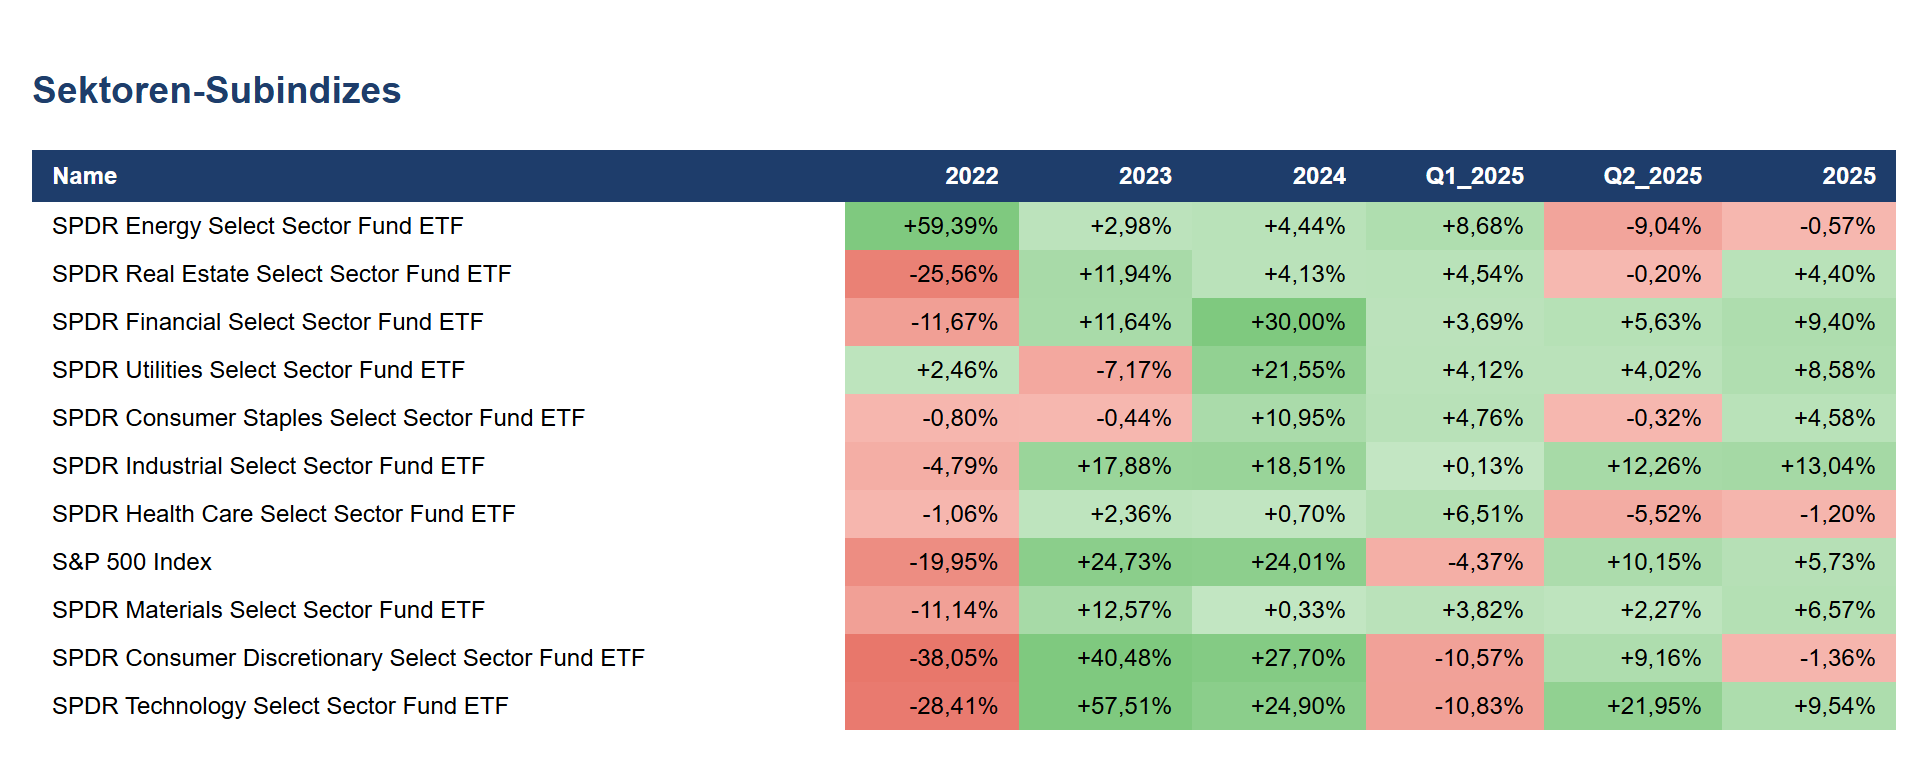
Was it all for nothing? Not quite. The dollar never recovered from this shock. The dollar index fell 10.8 percent in the first half of the year—its weakest start to a year since 1973—and lost as much as 14 percent against the Swiss franc. Capital sought out new avenues: European bank stocks rose by over 50 percent in the first half of the year, compared with about 14.5 percent for U.S. banks, and the DAX was also among the big winners, gaining just under 20 percent. The expectation was that capital would flow into the U.S.—instead, it increasingly flowed out.
On the interest rate front, the U.S. Federal Reserve held rates steady at 4.25–4.50 percent, while the ECB cut rates four times during the first half of the year, most recently in early June to 2.00 percent—and the SNB cut its key interest rate to 0.00 percent on June 19, citing the risk of deflation (May inflation: -0.1 percent) and the strength of the Swiss franc as reasons. In doing so, they deliberately left the door to negative interest rates ajar.
In mid-May, another historic event unfolded: Moody’s stripped the U.S. of its last remaining Aaa rating and downgraded it to Aa1—citing the structural deficit of about 9 percent of GDP. The 30-year yield briefly touched the 5 percent mark. And on June 13, shortly before the end of the first half of the year, Israel attacked Iran—the oil price posted its biggest single-day jump since the Russian invasion in 2022, and the stock markets fell. It was a preview of what the third quarter had in store.
In focus
What concerns us most about the first half of 2025 is not the tariff shock itself—such events have always occurred, and the markets have shown that they can absorb such shocks within weeks, as long as central banks and fiscal policy are standing by in the background. What concerns us is the dollar’s reaction. A country that imposes tariffs by decree, expecting capital to flow into the country as the trade balance improves—and instead sees its own currency lose value while gold and the eurozone benefit from the flight of capital— sends a signal that goes beyond day-to-day politics: Confidence in the U.S. as a safe haven is cracking.
We have repeatedly noted in previous issues of the Navigator that the high and still-rising levels of debt in Western countries will eventually take their toll. Moody’s downgrade in May is the first visible sign of this—but not the last. At the same time, the sell-off in the dollar shows that investors have begun to diversify their reserves, moving away from a concentration on a single currency and a single economy. This also explains why gold recorded its strongest inflows since 2020 in the first half of the year and why European markets—long shunned as “uninvestable”—were suddenly in demand again.
The DeepSeek shock in January, in turn, reminded us just how concentrated risk has become in today’s market. A single event in a single market segment—artificial intelligence—can wipe out nearly $600 billion in value within hours. That is no reason to abandon the topic of artificial intelligence, as its structural potential remains undisputed. However, it is a reason to remain aware of the concentration risks that have built up in the major U.S. indices over the years.
Outlook
The 90-day tariff reprieve granted in April will expire during the third quarter, and the escalation with Iran—which dominated the final days of June—has not yet subsided as of the end of the first half of the year. Both of these issues are areas of concern that are likely to shape the second half of the year. We expect that trade policy will continue to be used as a negotiating tool rather than a permanent state of affairs—the markets’ reaction in April showed that even a government committed to confrontation has its limits.
We do not expect a quick turnaround for the dollar. Structurally high debt, a hesitant central bank, and a trade conflict that is driving capital toward diversification all point more toward continued weakness than a V-shaped recovery. In this environment, gold and real assets remain a sensible addition to a portfolio—not as a bet on further price gains, but as insurance against precisely the kind of political surprise risk that has characterized this half-year.
“The stock market is a mechanism for transferring money from the impatient to the patient.”
EDURAN AG
Thomas Dubach